-
economicmargins
-
 July 28, 2026
-
 Global Economy
Stablecoins and the Future of Global Digital Finance
Stablecoins have emerged as a major innovation in digital finance, combining the efficiency of blockchain technology with the price stability of traditional assets. Unlike volatile cryptocurrencies like Bitcoin and Ethereum, stablecoins maintain value by pegging directly to fiat currencies or reserve assets. This stability makes them practical for everyday payments, cross-border transfers, decentralized finance (DeFi), and tokenized assets. Traditional payment systems rely on multiple intermediaries, driving up costs and causing settlement delays; stablecoins bypass these hurdles to enable instant, low-cost transfers over blockchain networks. By streamlining payment speed, transparency, and accessibility, stablecoins directly enhance financial inclusion and modernize global payments.
Evolution of Stablecoins
Stablecoins was first introduced around 2014, they gained widespread adoption between 2017 and 2020 as cryptocurrency exchanges sought stable trading assets. Their use expanded rapidly during the COVID-19 pandemic, supporting decentralized finance (DeFi), international settlements, digital commerce, and tokenized financial markets. The collapse of TerraUSD (UST) in 2022, accelerated global regulatory efforts to strengthen oversight, focusing on reserve backing, governance, consumer protection, and financial stability. Today, stablecoins are among the fastest-growing digital financial innovations, bridging traditional finance and blockchain-based payment systems.
Types of Stablecoins
Stablecoins maintain price stability through different mechanisms, which influence their degree of decentralization, transparency, and risk. They are generally classified into four main categories.
1. Fiat-Backed Stablecoins
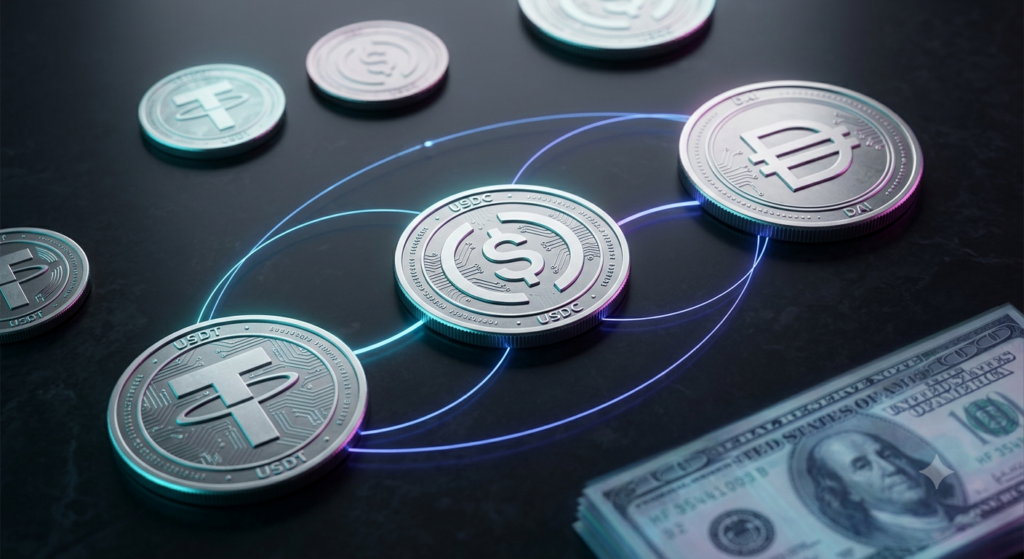
Fiat-backed stablecoins are the most widely used type, backed by fiat currency or highly liquid assets such as cash and short-term government securities. They are typically pegged 1:1 to a fiat currency, most commonly the U.S. dollar. Tether (USDT) and USD Coin (USDC) are the leading examples, widely used for cryptocurrency trading, international payments, and decentralized finance (DeFi). They offer high price stability but rely on centralized issuers to maintain reserves and ensure transparent redemption.
2. Cryptocurrency-Backed Stablecoins
Cryptocurrency-backed stablecoins are backed by digital assets such as Bitcoin or Ethereum. Because cryptocurrencies are volatile, these stablecoins are over-collateralized, requiring collateral worth more than the issued tokens. Smart contracts manage collateral and liquidate positions when necessary to maintain the peg. This decentralized model reduces reliance on intermediaries but is more complex and exposed to crypto market fluctuations. DAI, governed by MakerDAO, is the best-known example.
3. Commodity-Backed Stablecoins
Commodity-backed stablecoins are backed by physical assets such as gold or silver, with each token representing ownership of a specific amount of the commodity. Their value follows the market price of the underlying asset, offering greater stability and a potential hedge against inflation. Pax Gold (PAXG) and Tether Gold (XAUT) are leading examples backed by physical gold. These stablecoins require secure asset custody, regular audits, and transparent reserve reporting to maintain trust.
4. Algorithmic Stablecoins
Algorithmic stablecoins maintain price stability through automated algorithms rather than being fully backed by reserve assets. Using smart contracts, they adjust the token supply based on market demand—issuing new tokens when the price rises above the target and reducing supply when it falls below the peg. Although this approach is more capital-efficient because it requires little or no collateral, it relies heavily on market confidence. If confidence declines, the stabilization mechanism can fail. The collapse of TerraUSD (UST) in May 2022 highlighted these risks. As UST lost its dollar peg, both UST and its sister token LUNA collapsed, wiping out more than US$40 billion in market value. This event prompted regulators worldwide to strengthen oversight of stablecoins by introducing stricter requirements for transparency, reserve management, and investor protection.
Technical Architecture of Stablecoins
Stablecoins system combines blockchain networks, smart contracts, reserve management, and payment infrastructure to maintain a stable value and allow users to transfer money efficiently across the world.
a. Blockchain Infrastructure
Stablecoins are issued on blockchain networks such as Ethereum, Solana, Tron, and BNB Chain. These networks securely record every transaction in a transparent and tamper-resistant manner, allowing users to send and receive stablecoins without relying on traditional financial intermediaries such as banks.
b. Smart Contracts
A smart contract is a self-executing computer program stored on a blockchain that automatically performs predefined actions when certain conditions are met. In stablecoins, smart contracts automate important functions such as issuing new tokens, redeeming tokens, transferring funds, and managing collateral. This reduces costs, improves efficiency, and minimizes human intervention.
c. Reserve Management
For fiat-backed stablecoins, issuers maintain reserves such as cash, bank deposits, or short-term government securities to support the value of every token issued. Regular independent audits and public reserve reports help ensure that each stablecoin is fully backed, increasing transparency and user confidence.
d. Cross-Chain Interoperability
Many stablecoins are available on multiple blockchain networks. Using blockchain bridges and interoperability protocols, users can transfer stablecoins between different blockchains, making transactions more flexible, efficient, and accessible.
e. Tokenization
Stablecoins support the tokenization of real-world assets, such as real estate, bonds, or commodities, by converting them into digital tokens on a blockchain. This enables fractional ownership, faster transactions, and easier access to investment opportunities.
f. Payment Mechanisms
Stablecoins enable fast, low-cost, and 24/7 digital payments. They are widely used for domestic and international money transfers, online shopping, business payments, and decentralized finance (DeFi), making them an efficient alternative to traditional payment systems.
The process can be summarized in a single flow more clearly:
Blockchain Network (Ethereum/Solana/Tron/BNB Chain) → Smart Contracts (Issue, Redeem & Transfer Tokens) → Reserve Management (Cash & Government Securities Backing) → Cross-Chain Interoperability (Transfers Across Blockchains) → Tokenization (Real-World Assets into Digital Tokens) → Fast, Secure & Low-Cost Payments (P2P, Business, Cross-Border & DeFi)
Stablecoins vs. Central Bank Digital Currencies (CBDCs)
Although both stablecoins and Central Bank Digital Currencies (CBDCs) are digital forms of money, they differ significantly. Stablecoins are typically issued by private entities and backed by reserve assets, whereas CBDCs are issued and guaranteed by central banks as sovereign digital currency. While stablecoins promote innovation and private-sector efficiency, CBDCs prioritize monetary sovereignty, financial stability, and public trust. Both are expected to coexist, serving different roles within the evolving digital financial ecosystem.
Stablecoins in the Global Financial System
Stablecoins adoption has grown rapidly among banks, fintech companies, payment providers, and businesses for settlements, treasury management, and digital commerce. As of July 2026, the global stablecoin market was valued at approximately US$310 billion, with Tether (USDT) and USD Coin (USDC) accounting for the largest share of the market capitalization (Statista, 2026; data based on CoinGecko). The United States leads stablecoin adoption, while Europe, Singapore, Hong Kong, and several emerging economies are also expanding their use under evolving regulatory frameworks. Although retail adoption remains limited, increasing regulatory clarity and improvements in payment infrastructure are expected to drive broader.
Regulatory Push for Stablecoins
The rapid growth of stablecoins has prompted governments worldwide to develop regulatory frameworks that support innovation while addressing risks to financial stability, consumer protection, and financial integrity. The European Union’s Markets in Crypto-Assets (MiCA) Regulation, fully applicable since 2024, introduced comprehensive rules on licensing, reserve backing, governance, transparency, and redemption rights. Similarly, the U.S. GENIUS Act, enacted in 2025, established the first federal framework for payment stablecoins, requiring 100% reserve backing, regular disclosures, regulatory supervision, and compliance with anti-money laundering (AML) and counter-terrorism financing (CFT) standards.
Other jurisdictions, including the United Kingdom, Singapore, Hong Kong, and Japan, have also introduced or proposed stablecoin regulations, while international organizations such as the BIS, IMF, and FSB continue to promote global regulatory standards. Although these initiatives have improved market confidence and consumer protection, challenges remain, including regulatory differences across countries, oversight of decentralized and algorithmic stablecoins, and cross-border enforcement. Greater international coordination will be essential to support the safe and sustainable growth of stablecoins.
Future Outlook
The next phase of stablecoin development may involve deeper integration with mainstream financial services. Banks, payment companies, fintech firms, and asset managers are increasingly exploring tokenized deposits, blockchain settlement systems, and programmable financial products. As regulation becomes more clearer and technology continues to mature, stablecoins may become an essential component of global payment infrastructure rather than simply a niche cryptocurrency product. Instead of replacing banks, stablecoins are more likely to complement existing financial institutions by modernizing payment rails, improving settlement efficiency, and expanding financial access.
Stablecoin impact in Global Payments can be listed as follows;
- A New Payment Infrastructure: By reducing reliance on intermediaries, stablecoins will enable instant settlements, lower transaction costs, and programmable payments through smart contracts.
- Growing Adoption by Fintech Companies: Fintech firms has been increasingly adopting stablecoins to improve payment efficiency, reduce costs, and expand cross-border financial services.
- Cross-Border Transactions: Stablecoins will continue to provide a faster and more affordable alternative to traditional international payment systems, benefiting trade, remittances, and financial inclusion.
- Reducing Financial Friction: Stablecoins will further reduce settlement delays, transaction costs, and operational complexity, making global payments more efficient for businesses and consumers.
Challenges and Risks
Despite their advantages, stablecoins are not without challenges. Their reliability depends on the quality and transparency of reserve assets. The TerraUSD collapse in 2022 highlighted the risks associated with poorly designed stabilization mechanisms.
Other important concerns are:
- Regulatory uncertainty across jurisdictions.
- Anti-money laundering (AML) and combating the financing of terrorism (CFT) compliance.
- Cybersecurity and operational risks.
- Consumer protection.
- Financial stability risks if stablecoins become widely used without appropriate oversight.
- Potential effects on commercial bank deposits and monetary policy transmission.
Recognizing these challenges, governments and international organizations across jurisdictions have to develop more strong regulatory frameworks to ensure stablecoins remain safe, transparent, and resilient.
Policy Recommendations
To maximize the benefits of stablecoins while minimizing financial, operational, and regulatory risks, policymakers should adopt a balanced and comprehensive regulatory framework that promotes innovation, protects consumers, and preserves financial stability.
- Establish comprehensive regulations to ensure full reserve backing, transparent reserve disclosures, and regular independent audits.
- Strengthen consumer protection by guaranteeing redemption rights and enhancing transparency.
- Enforce AML/CFT compliance through robust anti-money laundering and counter-terrorism financing requirements.
- Enhance risk management and cybersecurity standards to improve operational resilience and safeguard users.
- Promote responsible innovation by providing clear licensing and supervisory frameworks that support technological development.
- Foster international cooperation to harmonize regulatory standards, reduce regulatory arbitrage, and ensure cross-border financial stability.
- Support balanced regulation that encourages innovation while maintaining financial stability and market integrity.
Conclusion
Stablecoins represent one of the most practical applications of blockchain technology, combining the stability of fiat currencies with the efficiency of decentralized networks. They can transform global payments by reducing transaction costs, improving cross-border commerce, and expanding financial inclusion.
However, their long-term success will depend on effective regulation, transparent reserve management, robust cybersecurity, and strong consumer protection. Policymakers must strike a balance between fostering innovation and safeguarding financial stability to address risks such as illicit finance, operational failures, and potential impacts on monetary policy and the banking system. With an appropriate regulatory framework, stablecoins can become a key component of the global digital economy, complement traditional financial institutions and support a more efficient, inclusive, and interconnected financial system.
References
Bank for International Settlements. (2024). Annual Economic Report 2024. https://www.bis.org/
European Parliament & Council of the European Union. (2023). Regulation (EU) 2023/1114 on markets in crypto-assets (MiCA). https://eur-lex.europa.eu/eli/reg/2023/1114/oj
Financial Stability Board. (2023). High-level recommendations for the regulation, supervision and oversight of global stablecoin arrangements. https://www.fsb.org/
International Monetary Fund. (2024). Global Financial Stability Report. https://www.imf.org/
Statista. (2026). Market capitalization of stablecoins worldwide (based on CoinGecko data). https://www.statista.com/statistics/1315474/biggest-stablecoin-in-the-world/
Andreessen Horowitz (a16z crypto). (2024). A guide to stablecoins: What, why, and how. https://a16zcrypto.com/stablecoins-guide/
Broner, S. (2025). How stablecoins will eat payments, and what happens next. Andreessen Horowitz (a16z crypto). https://a16zcrypto.com/posts/article/how-stablecoins-will-eat-payments-and-what-happens-next/
U.S. Congress. (2025). Guiding and Establishing National Innovation for U.S. Stablecoins (GENIUS) Act.